Pay Now

Easily pay your M&M invoice online

White house with a gray roof and two skylights
Financing

Easy and simple financing for your roof

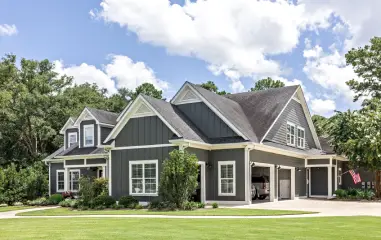
Craftsman house with gray shingles and teal siding
Roof Insurance

Pay for your new roof with Insurance

Two roofers installing brown shingles
Residential Roofing

Trusted Residential Roofing Contractor Services

Craftsman house with gray shingles and teal siding
Commercial Roofing

TPO, metal & flat roofing for businesses

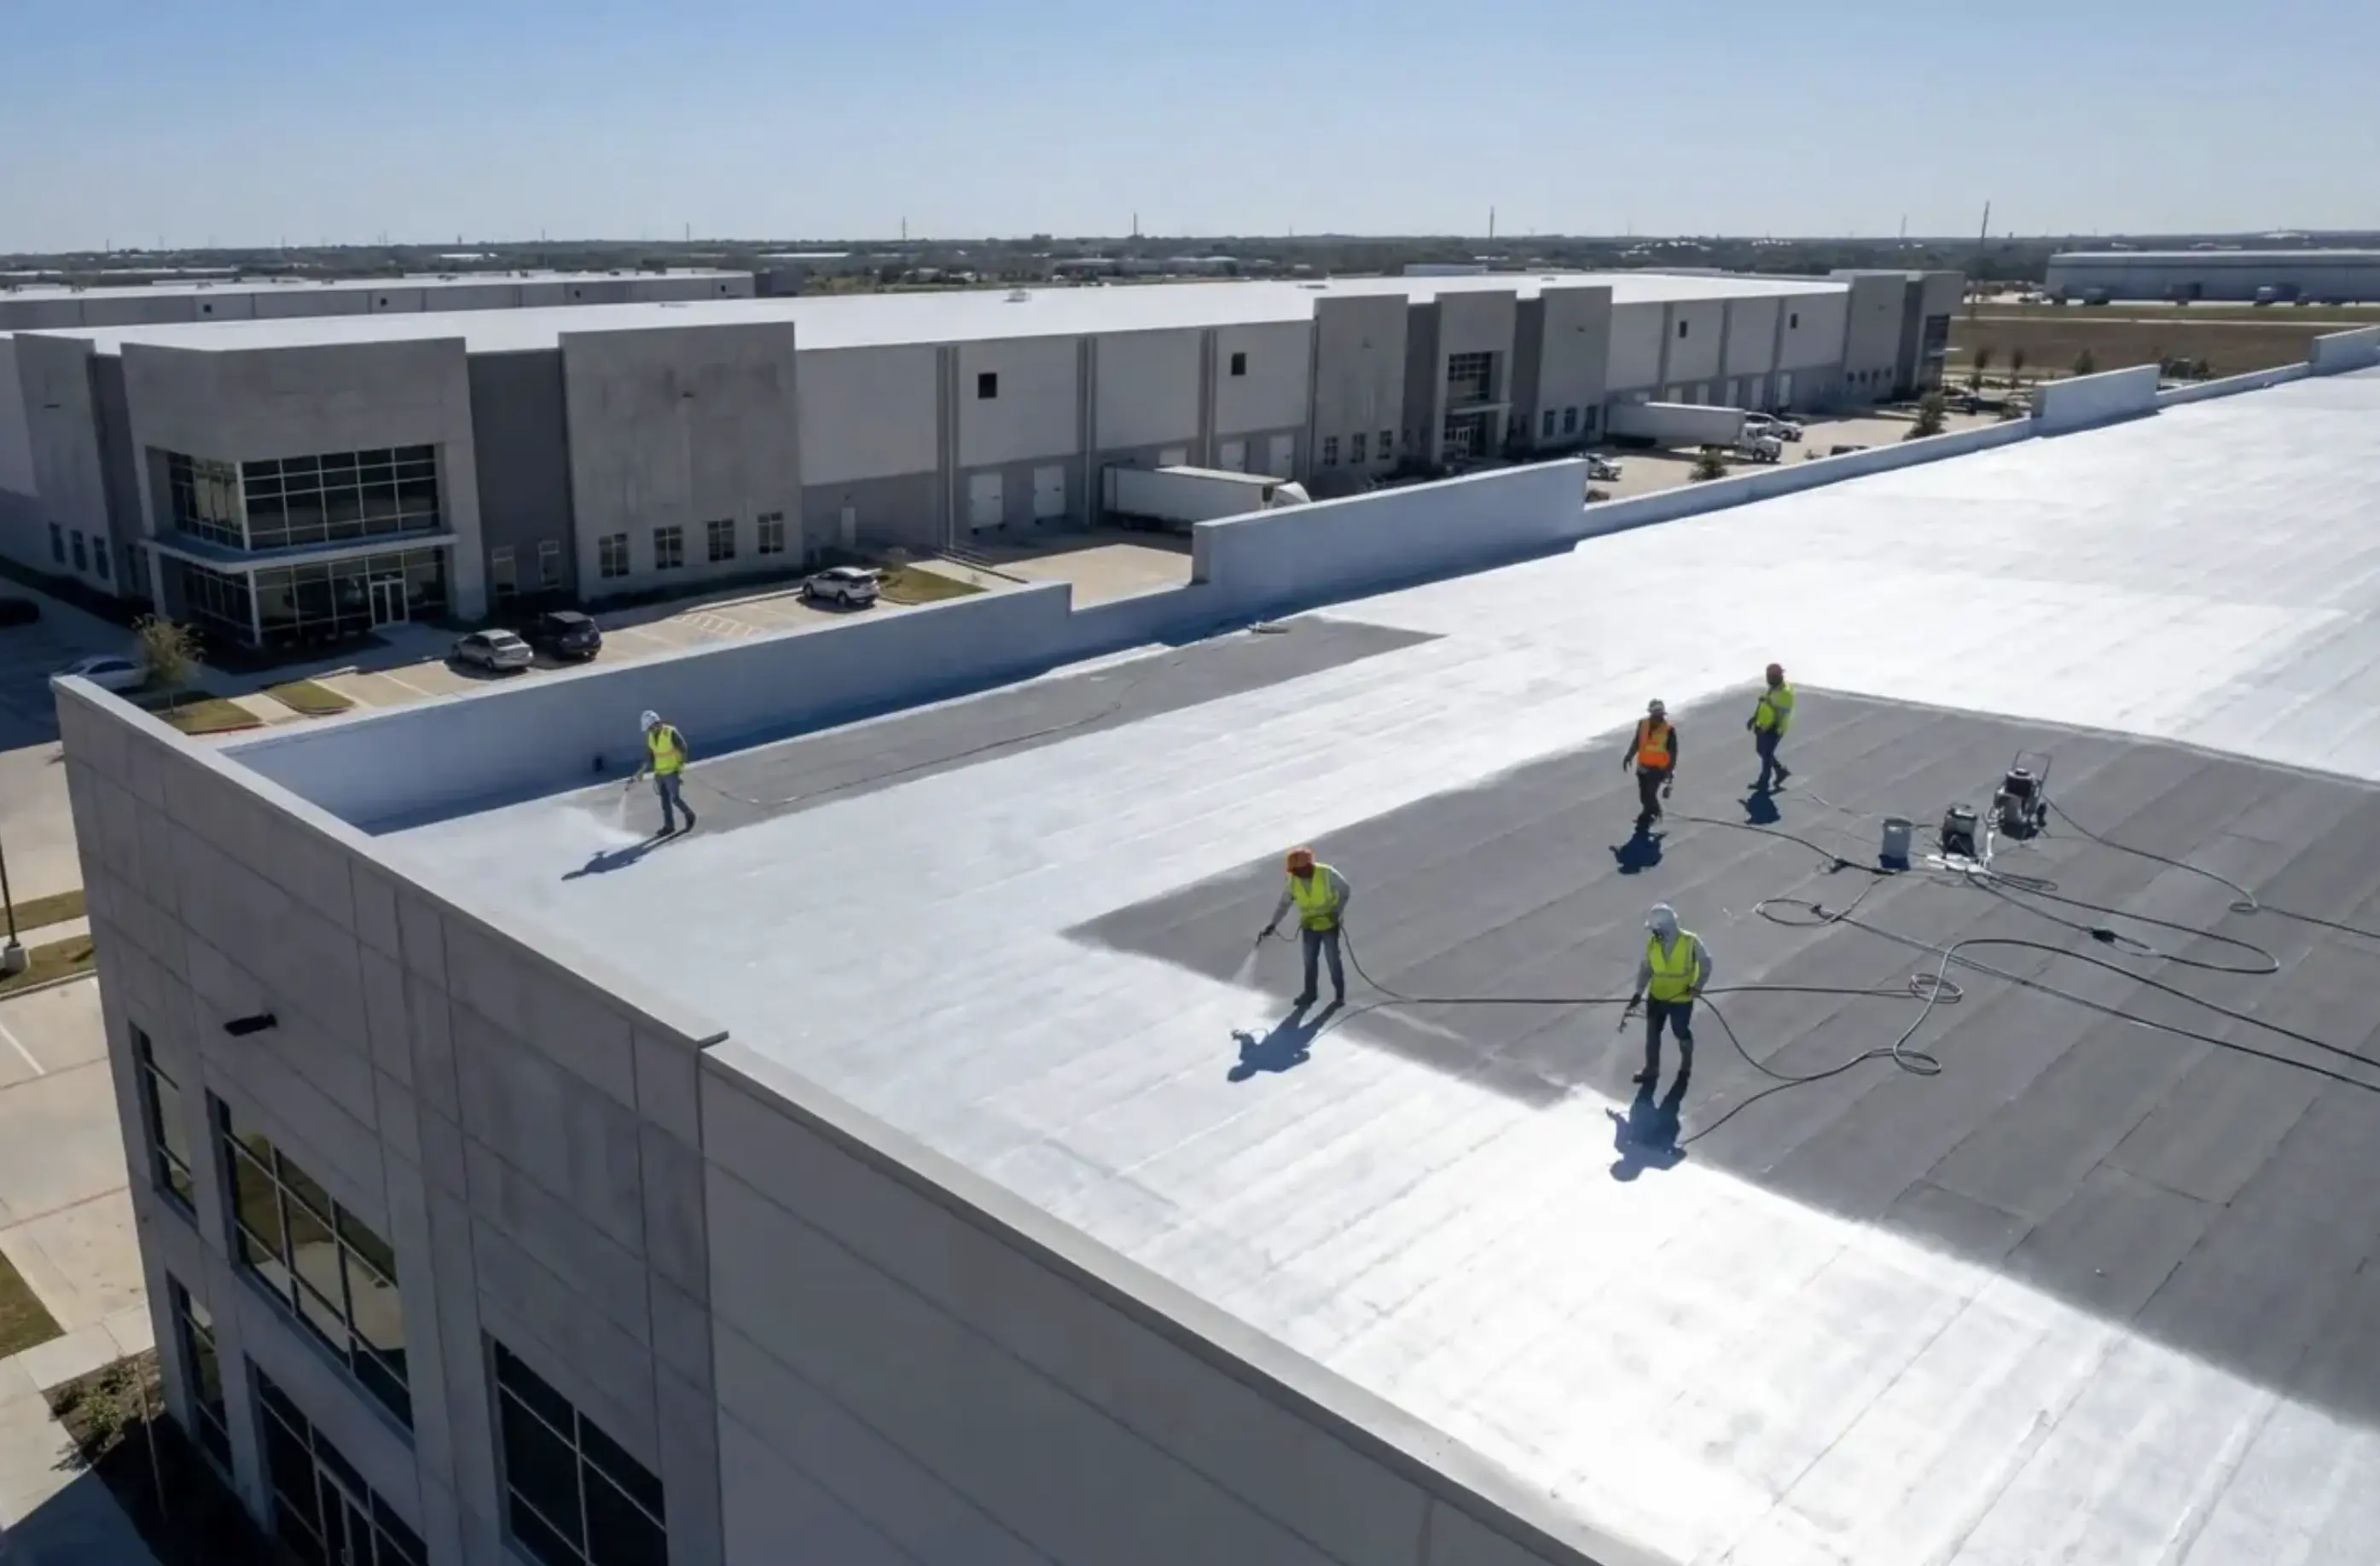
Crew coating a commercial flat roof white
Multi-Family Roofing

Roofing for apartments, HOAs & multi-unit properties

Two roofers installing brown shingles
Roof Types
Let M&M Roofing’s expert roofers help you decide
White house with a gray roof and two skylights
Siding

Trusted Siding Contractor Services

Dark gray two-story house with white trim
Windows

Trusted Windows Contractor Services

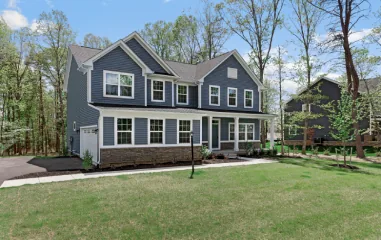
Blue two-story house with white trim and a stone base
Gutters

Trusted Gutters Contractor Services

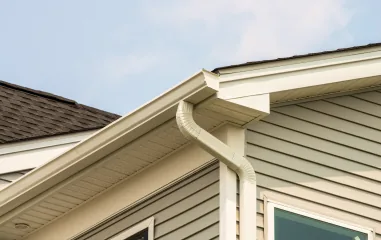
Cream gutters and vinyl siding
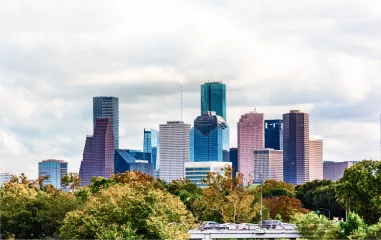
Houston Roofing

Our HQ · Katy, Sugar Land, Pearland & The Woodlands

Houston skyline
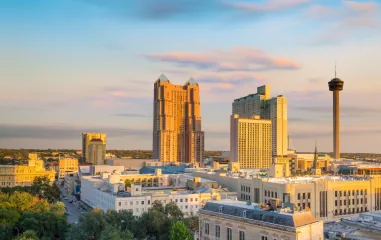
San Antonio Roofing

New Braunfels, Schertz, Cibolo & Helotes

San Antonio skyline at sunset
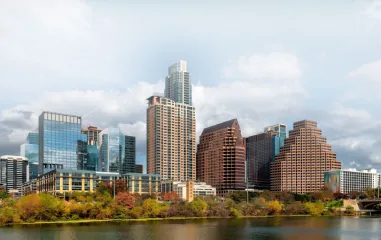
Austin Roofing

Round Rock, Cedar Park, Pflugerville & Georgetown

Austin skyline
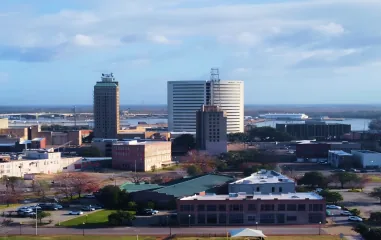
Beaumont Roofing

Nederland, Port Arthur & the Golden Triangle

Beaumont skyline along the river
Seabrook Roofing

Clear Lake & the Bay Area

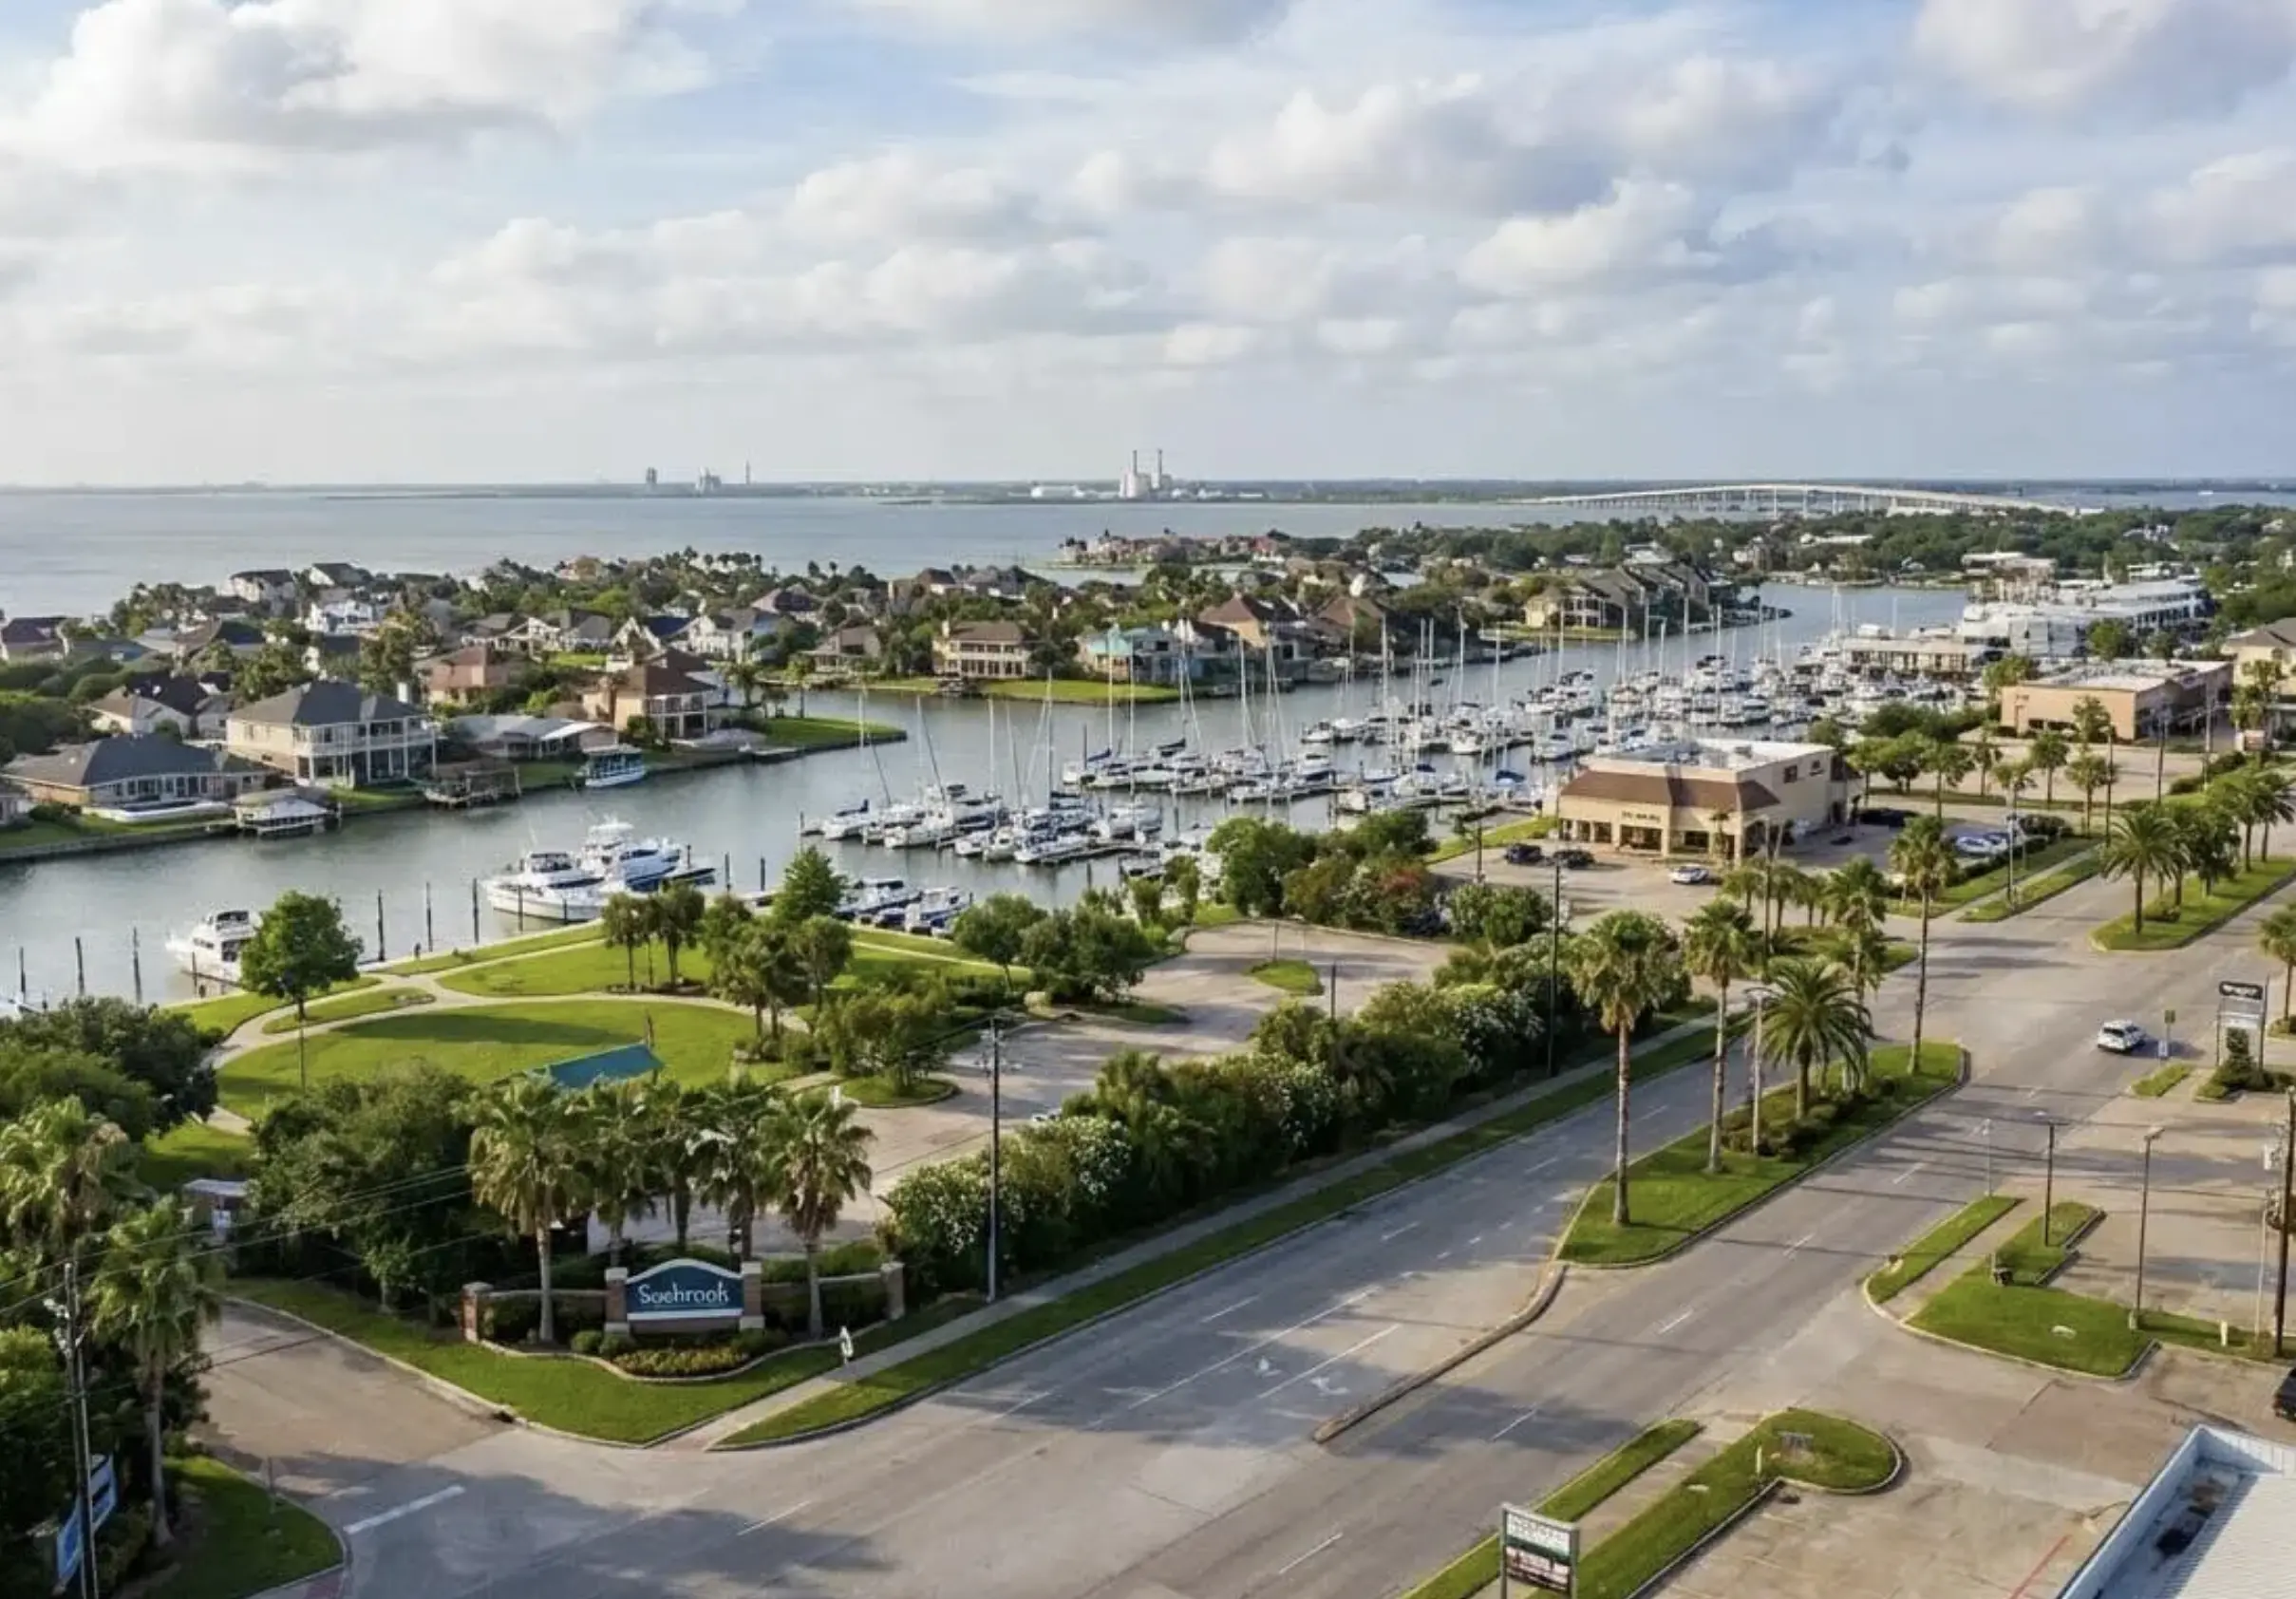
Aerial view of the Seabrook marina and canals
Lake Charles Roofing

Serving Southwest Louisiana

Lake Charles waterfront with a teal glass tower
Why We Are Better

Family-owned since 1983 · lifetime roof warranty

Gray shingle roof with two white dormers
Reviews

Rated 4.9 · 1,400+ Google reviews

Aerial view of a dark shingle roof on a large house
Recent Work

Photos & videos of recent projects

Aerial view of a dark shingle roof on a large house
Referral Program

Refer a neighbor, get rewarded

Handshake over a small model house

Roof Insurance Claims Assistance in Texas & Louisiana

★★★★★ 4.91,400+ Google reviews40+ years in Texas & Louisiana

Serving Texas & Louisiana since 1983

Coverage usually turns on the cause of damage, not just whether the roof leaks. Before you file: protect the property, document the event, and have the roof professionally inspected.

Free storm damage inspection

Request a Call Back

No cost, no obligation. A local M&M inspector will call you back.

This field is for validation purposes and should be left unchanged.
Name
Address

Free inspection · No obligation · Serving Texas & Louisiana since 1983

Privacy Policy · Terms & Conditions

40+ years in Texas & Louisiana

4.9★ · 1,400+ Google reviews

6 local offices

GAF Master Elite certified

Who should you call first?

For most non-emergency situations, start with a qualified local roofer. An inspection keeps you from opening a claim for ordinary wear, deferred maintenance, or damage that lands below your deductible.

Call a roofer first when…

  • You're not sure whether real damage exists
  • The roof isn't open to the weather
  • You want photos and a repair assessment in hand

Act immediately when…

  • Water is entering the home
  • A tree or debris has opened the roof
  • The property is unsafe or unsecured

Should you file? Filing usually makes sense when verified covered damage is likely to exceed your deductible. It usually doesn't when the issue is wear, maintenance, or a small repair. See coverage →

What roof damage is commonly covered?

Homeowners policies usually cover sudden, accidental damage from a covered peril. They generally don't cover predictable deterioration or neglected maintenance.

Commonly covered*

  • Hail and wind damage
  • Fallen trees and debris
  • Fire and other sudden events
  • Some storm-related leaks

Commonly excluded*

  • Age and normal wear
  • Neglected maintenance
  • Long-term or repeated leaks
  • Faulty installation or materials

*Examples only. Your insurer determines coverage under the terms, exclusions, and limits of your policy.

Four terms explain most claim payments

01

Deductible

The portion you pay before policy benefits apply. Yours, always.

02

ACV

Actual cash value — replacement cost minus depreciation for age and condition.

03

RCV

Replacement cost value — what it costs to replace with comparable materials today.

04

Depreciation

Value withheld for age or wear. Some of it is recoverable after the work is done.

Eight steps, from storm to restored roof

Every claim moves through roughly this sequence. Knowing the order is most of what keeps a claim from stalling.

01

Protect the property

Stop the water, tarp what's open, keep receipts.

02

Document the damage

Photograph the roof, interior, and storm date.

03

Get a roof inspection

Confirm real damage exists before you file.

04

Notify your insurer

Report the loss per your policy's instructions.

05

Meet the adjuster

Have your roofer up there documenting too.

06

Review the scope

Compare what's approved to what's required.

07

Complete approved work

Pick materials, pull permits, keep records.

08

Recover depreciation

Submit final invoices to release withheld value.

Honest note: We can document your roof and meet your adjuster, but we can't tell you what your policy covers. That call belongs to your insurer — anyone promising otherwise is selling you something.

An insurance scope and a contractor estimate are not the same document

The insurer's scope

Documents what the carrier approved under the policy, priced with its own software and depreciation. It is a coverage document, not a construction plan.

The contractor's estimate

Describes the work and materials actually needed to restore the roof to code — including details a desk review can miss, like decking, flashing, or ventilation.

If something looks incomplete Request the written scope, compare it against documented roof conditions, and submit construction-related omissions through the insurer's own process. Document, don't argue.

Choose your state

Texas and Louisiana handle deductibles, timelines, and contractor licensing differently. Only read the half that applies to you.

Texas roof claims

Deductibles, carrier timelines, and TWIA

  • Texas law requires homeowners to pay their policy deductible — it cannot be waived or absorbed.
  • Carrier response periods have catastrophe-related exceptions after declared events.
  • TWIA windstorm procedures are distinct from standard private coverage.

Louisiana roof claims

Named-storm deductibles and licensed contractors

  • Named-storm deductibles are often percentage-based, not a flat dollar amount.
  • Verify your roofer holds the appropriate Louisiana contractor license.
  • Roofers may not act as unlicensed public adjusters on your claim.

A roofer should document your roof, not promise you coverage

What M&M can do

Roof inspections, damage photos, construction estimates, adjuster meetings, documented scope omissions, permitted repairs and replacement, and completion records for your file.

What no roofer can do

Determine coverage, interpret your policy, negotiate as a public adjuster, waive your deductible, or promise you a claim outcome. If you hear those promises, keep shopping.

40+

Years in business

4.9 ★

Google rating

6

Gulf Coast offices

Insured

Fully licensed crews

See the damage. See the finished roof.

Two-story house with a dark shingle roof and lit windows at dusk

Roof replacement

Texas & Louisiana

Row of townhomes with gray shingle roofs and balconies

Multi-family roofing

Texas & Louisiana

White house with clapboard siding, dormers, and a brick chimney

Roofing & siding

Texas & Louisiana

Homeowners describe the experience

★ 4.9 average · 1,400+ Google reviews

Jacob Kempnich
Jacob Kempnich
★★★★★
We just had our roof replaced by M&M Roofing in Clearlake and were very pleased with their work. Michael McCollom did a great job of explaining everything to us beforehand, including discussing options and plans, the pricing and scope was very fair and reasonable. Once we signed the contract for the work, he communicated with us promptly about dates and expectations. The crew showed up and they were extremely fast and efficient. The roof looks great, and we couldn't be happier. We highly recommend M&M Roofing Siding & Windows.
Steve Hargis
Steve Hargis
★★★★★
We had M&M come out to repair a couple of leaks in our covered patio. Greg was super helpful in diagnosing the issues, providing lots of information on how best to make the repairs and options for what we needed.


The work was completed in one day and Greg came out to make sure the crew was doing everything the way he wanted. The whole process was really great. Very professional from start to finish. Thanks M&M.
Cassandra Lazos
Cassandra Lazos
★★★★★
I recently had the pleasure of working with M&M for siding work on my house, and I must say, the experience exceeded all my expectations. From the get-go, the level of customer service was simply outstanding. A special shoutout to Sam, our representative, who was not only professional and knowledgeable but also incredibly attentive to our needs.

Sam went above and beyond to ensure that all our questions were answered, and our concerns addressed, making the entire process smooth and stress-free.
Rachel Maddoux
Rachel Maddoux
★★★★★
Tim did a great job. He picked out tile that exactly matched my roof. I only had to replace a portion of …
Brittney Richard
Brittney Richard
★★★★★
I cannot say enough good things about this roofing company! From start to finish, the entire experien…
Sam Trujillo
Sam Trujillo
★★★★★
Chris P. was prompt and knowledgeable about his product and shared wonderful insight as t…
Keith Blackford
Keith Blackford
★★★★★
Honest, professional, easy to deal with! Highly recommend.
Bill G
Bill G
★★★★★
Replaced our mid-1980s residential siding with a major-branded cement-fiber product in August…
Charlotte Childress
Charlotte Childress
★★★★★
M&M has been there for me through a new roof, siding, and gutters… they are professionals th…
Jingting Yang
Jingting Yang
★★★★★
We recently replaced our 20-year-old roof using M&M Roofing, and we couldn’t be happier with our…

Roof insurance claim FAQs

Unless your policy requires immediate reporting, or the home is unsafe, a professional inspection first helps you decide whether filing makes sense at all.

It depends on the cause and extent of the damage, your policy language, your deductible, and whether a repair is feasible. Partial approvals are common.

No. In Texas that is illegal, and everywhere it's a red flag. You are responsible for the deductible stated in your policy.

Request the written scope, compare it with documented roof conditions, and submit construction-related omissions through your insurer's process.

Policies set their own notice deadlines, and state law sets outer limits. File as soon as you have documentation — waiting invites a wear-and-tear denial.

That's your carrier's decision, not ours. It's one reason we recommend an inspection before filing, so you know what you're actually claiming.

Find out what your roof actually needs

Pick the M&M office nearest you and request a no-obligation inspection. We'll document what we find and hand you the photos, whether or not you file.

★ 4.91,400+ reviewsTexas & Louisiana since 1983